Part 3 of a 6-part series on understanding your net proceeds as a seller.
An online estimate isn’t a net sheet — Part 1 covered why. Part 2 walked through every line item that separates the two. This week, the question underneath both of those posts: what net proceeds will you actually walk away with?
Most sellers think of a net sheet as paperwork — something escrow hands you near the end, mostly for the record. In practice, it’s the answer to the only question that matters before you list: what will your net proceeds actually be?
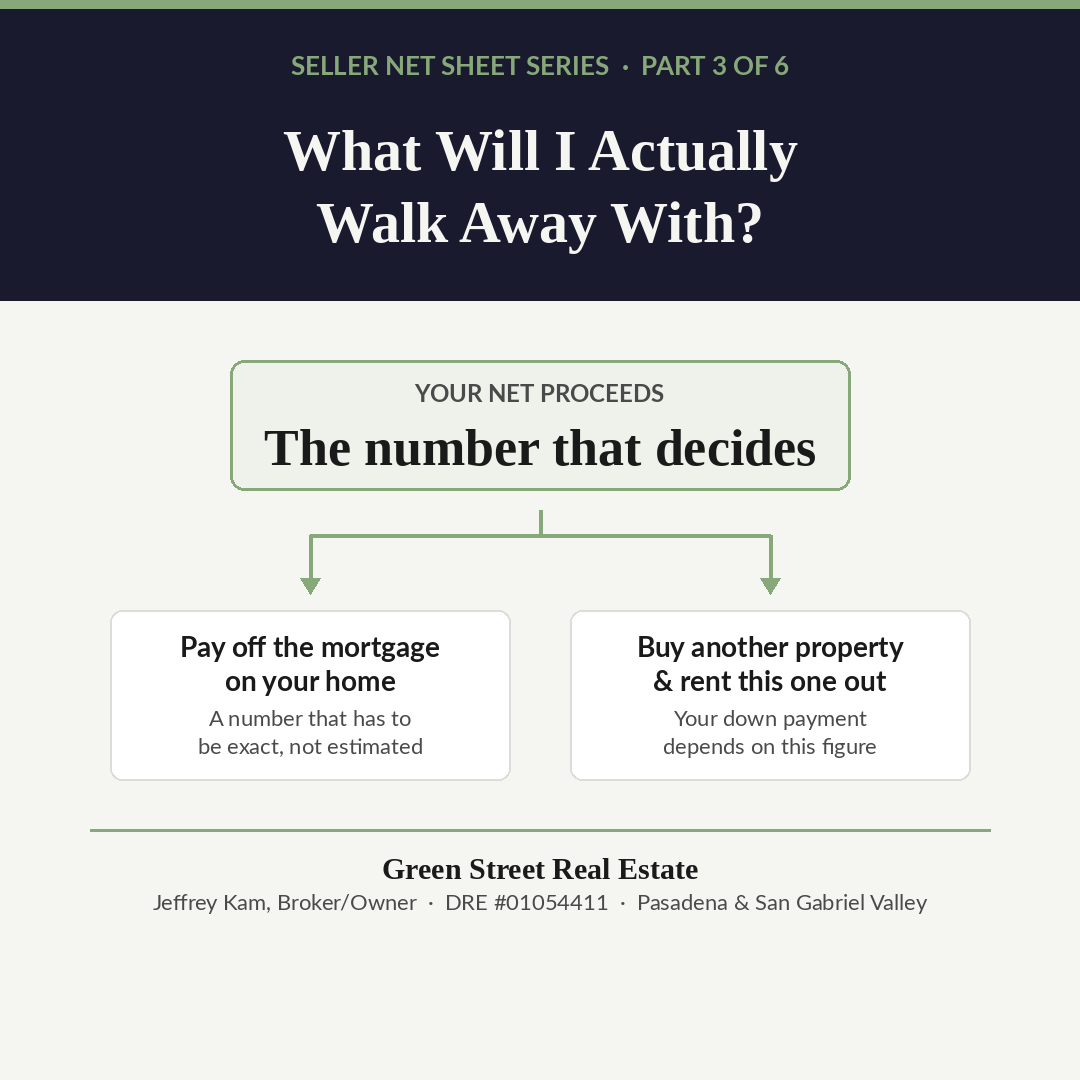
Net Proceeds Are the Number That Decides
That’s not a rhetorical question. For most sellers, net proceeds aren’t just informational — they’re load-bearing. They determine what happens next.
A seller I worked with recently sold in the $700K–$900K range with a specific number in mind for his proceeds. He had two paths depending on that number. Pay off the mortgage on his personal residence outright. Or use the proceeds to buy a second property and rent out the one he was living in. Either path was viable — but only one of them, at a given price point.
The net proceeds he was picturing came in lower than expected. Two things moved it. First, his mortgage payoff was higher than what he remembered from his last statement. Payoff figures include per diem interest calculated to the closing date. If there’s a second loan or a HELOC on the property, that gets paid off too. Second, inspection turned up items that led to negotiated repair credits, which came directly off his proceeds. Neither of these was unusual. Both were larger than he’d budgeted for, because he hadn’t budgeted for them at all. He’d been working off sale price, not net proceeds. (For the full list of what factors into that number, see Part 2 of this series.)
The plans themselves weren’t the problem. The problem was that he’d built them on a number that hadn’t been verified. A mortgage payoff and a purchase decision are the kind of commitments that don’t have much room for “roughly.” When the actual net sheet came in lower than the mental math, the choice between paying off one mortgage and taking on a new one got a lot narrower.
Verify That Number Before You Commit
This is the actual function of a net sheet: it turns a plan that depends on money into a plan that’s grounded in an actual number, not a sale price or an estimate (see Part 1 on why those two diverge). The figure left after payoff, commission, taxes, fees, and any credits — the net proceeds that are actually yours to work with.
That’s also why net proceeds are worth confirming early, not after you’ve accepted an offer. If your next move — paying off debt, buying another property, funding a purchase elsewhere — depends on your proceeds, the time to know the real number is before you’re deciding between two paths, not after one of them has quietly closed.
If you’re weighing a sale and have a specific plan riding on the outcome, it’s worth running the actual numbers before you commit to either direction.
Next in this series: the number your online estimate won’t show you — and why FSBO sellers feel the gap first.
Jeffrey Kam | Broker/Owner, Green Street Real Estate | DRE #01054411
Serving Pasadena and the San Gabriel Valley